Covered cause
A policy can treat storm damage differently from wear, deterioration or excluded conditions. Roof age alone does not establish a covered loss.
Understand the difference between the roof work, policy coverage and the amount paid.
A roof inspection addresses the physical condition. Insurance coverage depends on the cause, policy terms and the insurer’s claim decision. The deductible and payment terms then affect what the owner pays. Keeping those questions separate makes the repair conversation clearer.
A policy can treat storm damage differently from wear, deterioration or excluded conditions. Roof age alone does not establish a covered loss.
The deductible is the amount retained by the policyholder under the policy terms. A roof repair price above it does not by itself establish coverage.
Actual cash value can account for depreciation. Replacement-cost terms can include conditions before additional payment is available. The actual policy controls.
The failed covering, flashing and layers underneath determine the physical work. Claim paperwork and a payment figure do not rebuild those details. If opening the roof reveals concealed damage, the scope and any associated claim question need to be addressed through the appropriate parties.
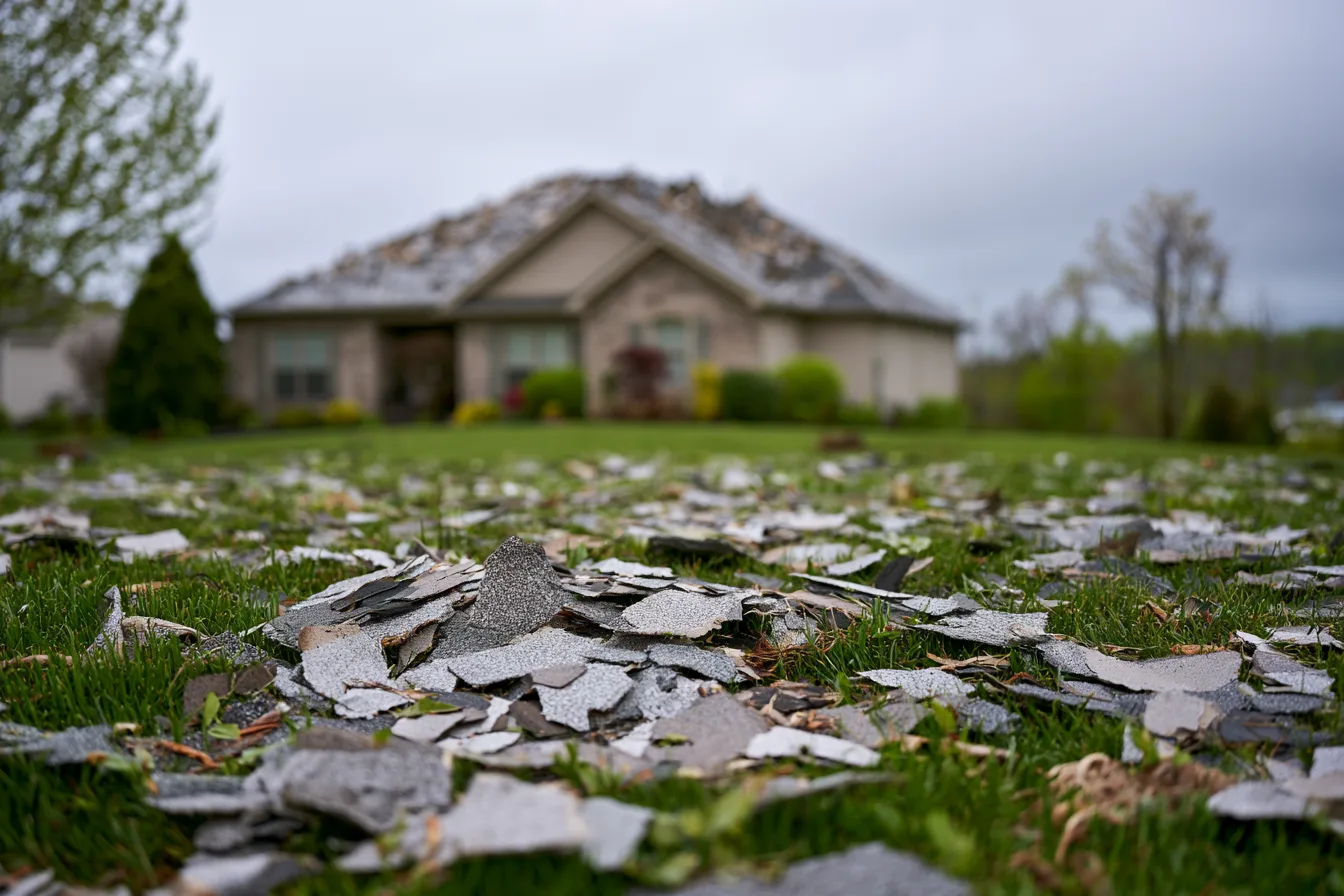
Tell us what happened and when you noticed a change. Report a potential loss according to the policy’s requirements and keep the insurer informed through its claim process. Stay off a damaged roof and away from wet electrical fixtures.
What is damaged and what repair can reconnect.
Whether the cause and work fall within the policy.
Deductible, depreciation and actual claim terms.
No. A roofer assesses the roof and explains work. Coverage and payment are the insurer’s decisions under the policy.
Yes. A free roof inspection can help explain the roof condition. It does not replace the policy’s reporting requirements or decide coverage.
Request a free inspection for the roof concern at your De Soto property.